In boardrooms of the manufacturing and logistics companies we talk to, the question has shifted from whether to deploy autonomous robots to when and how fast.
The industrial labor shortage isn't going away. U.S. manufacturers have carried roughly half a million or more open jobs every month for six years, per BLS job openings data. The demand has been clear for a long time; now, for the first time, the technology is beginning to catch up.
But robotics isn't one market, and it won't be distributed like LLMs, which reach customers through a simple API. Every robotics customer has distinct environments, requirements, and metrics. That shapes our core belief about the space: the biggest companies will be built where deployment meets the customer, not just where the models get made. Here's how we see the landscape.
Why Demand Is Real and Urgent
The case for robots in industrial settings has always been intuitive. The jobs are dangerous, repetitive, and increasingly hard to fill. In manufacturing, logistics, energy, and healthcare, labor shortages are acute. In trucking, the shortage already tops 80,000 drivers and is projected to reach 160,000 by 2030, even as total industry employment sits below its 2022 peak. In energy, 2.4 workers are nearing retirement for every new entrant under 25 across advanced economies, per the IEA.
Why Today's Robots Still Fall Short
Most industrial robots today are confined to simple, highly structured tasks: palletizing, pick-and-place, and fixed assembly lines. Every new task requires painstaking manual programming, extensive on-site testing, and significant integration work. The robot arm itself is typically only 25 to 40 percent of the cost of a working deployment; integration, tooling, and safety systems make up the rest, and they recur every time the task changes. That math kills the economics for all but the highest-volume applications.
More fundamentally: because today's robots are statically programmed, they fail the moment their environment changes. This excludes enormous swaths of potential use cases that represent real, latent demand in the physical world.
The Shift: Foundation Models Change the Equation
What's different now is the emergence of generalizable foundation models for robotics: models that can learn across tasks, adapt to new hardware, and transfer capabilities without being reprogrammed from scratch.
Physical Intelligence*, where we're investors, is building at this layer. Early pilots are showing deployment times shrinking from months to days, with models transferring quickly across new tasks and robot types.
The dream state is no longer science fiction: bring hardware in, turn it on, train briefly, and it works. Eventually, it should be able to learn and adapt like a new hire would.
Foundation models are the layer getting the most attention, but there’s a rich ecosystem behind them, from data collection to developer tooling to on-device compute to simulation. All of it must come together to get robots working in the real world.
The Robotics Stack: How We See the Market
We see the market in two parts: the infrastructure required to make deployment possible, and the applications that become viable as a result.
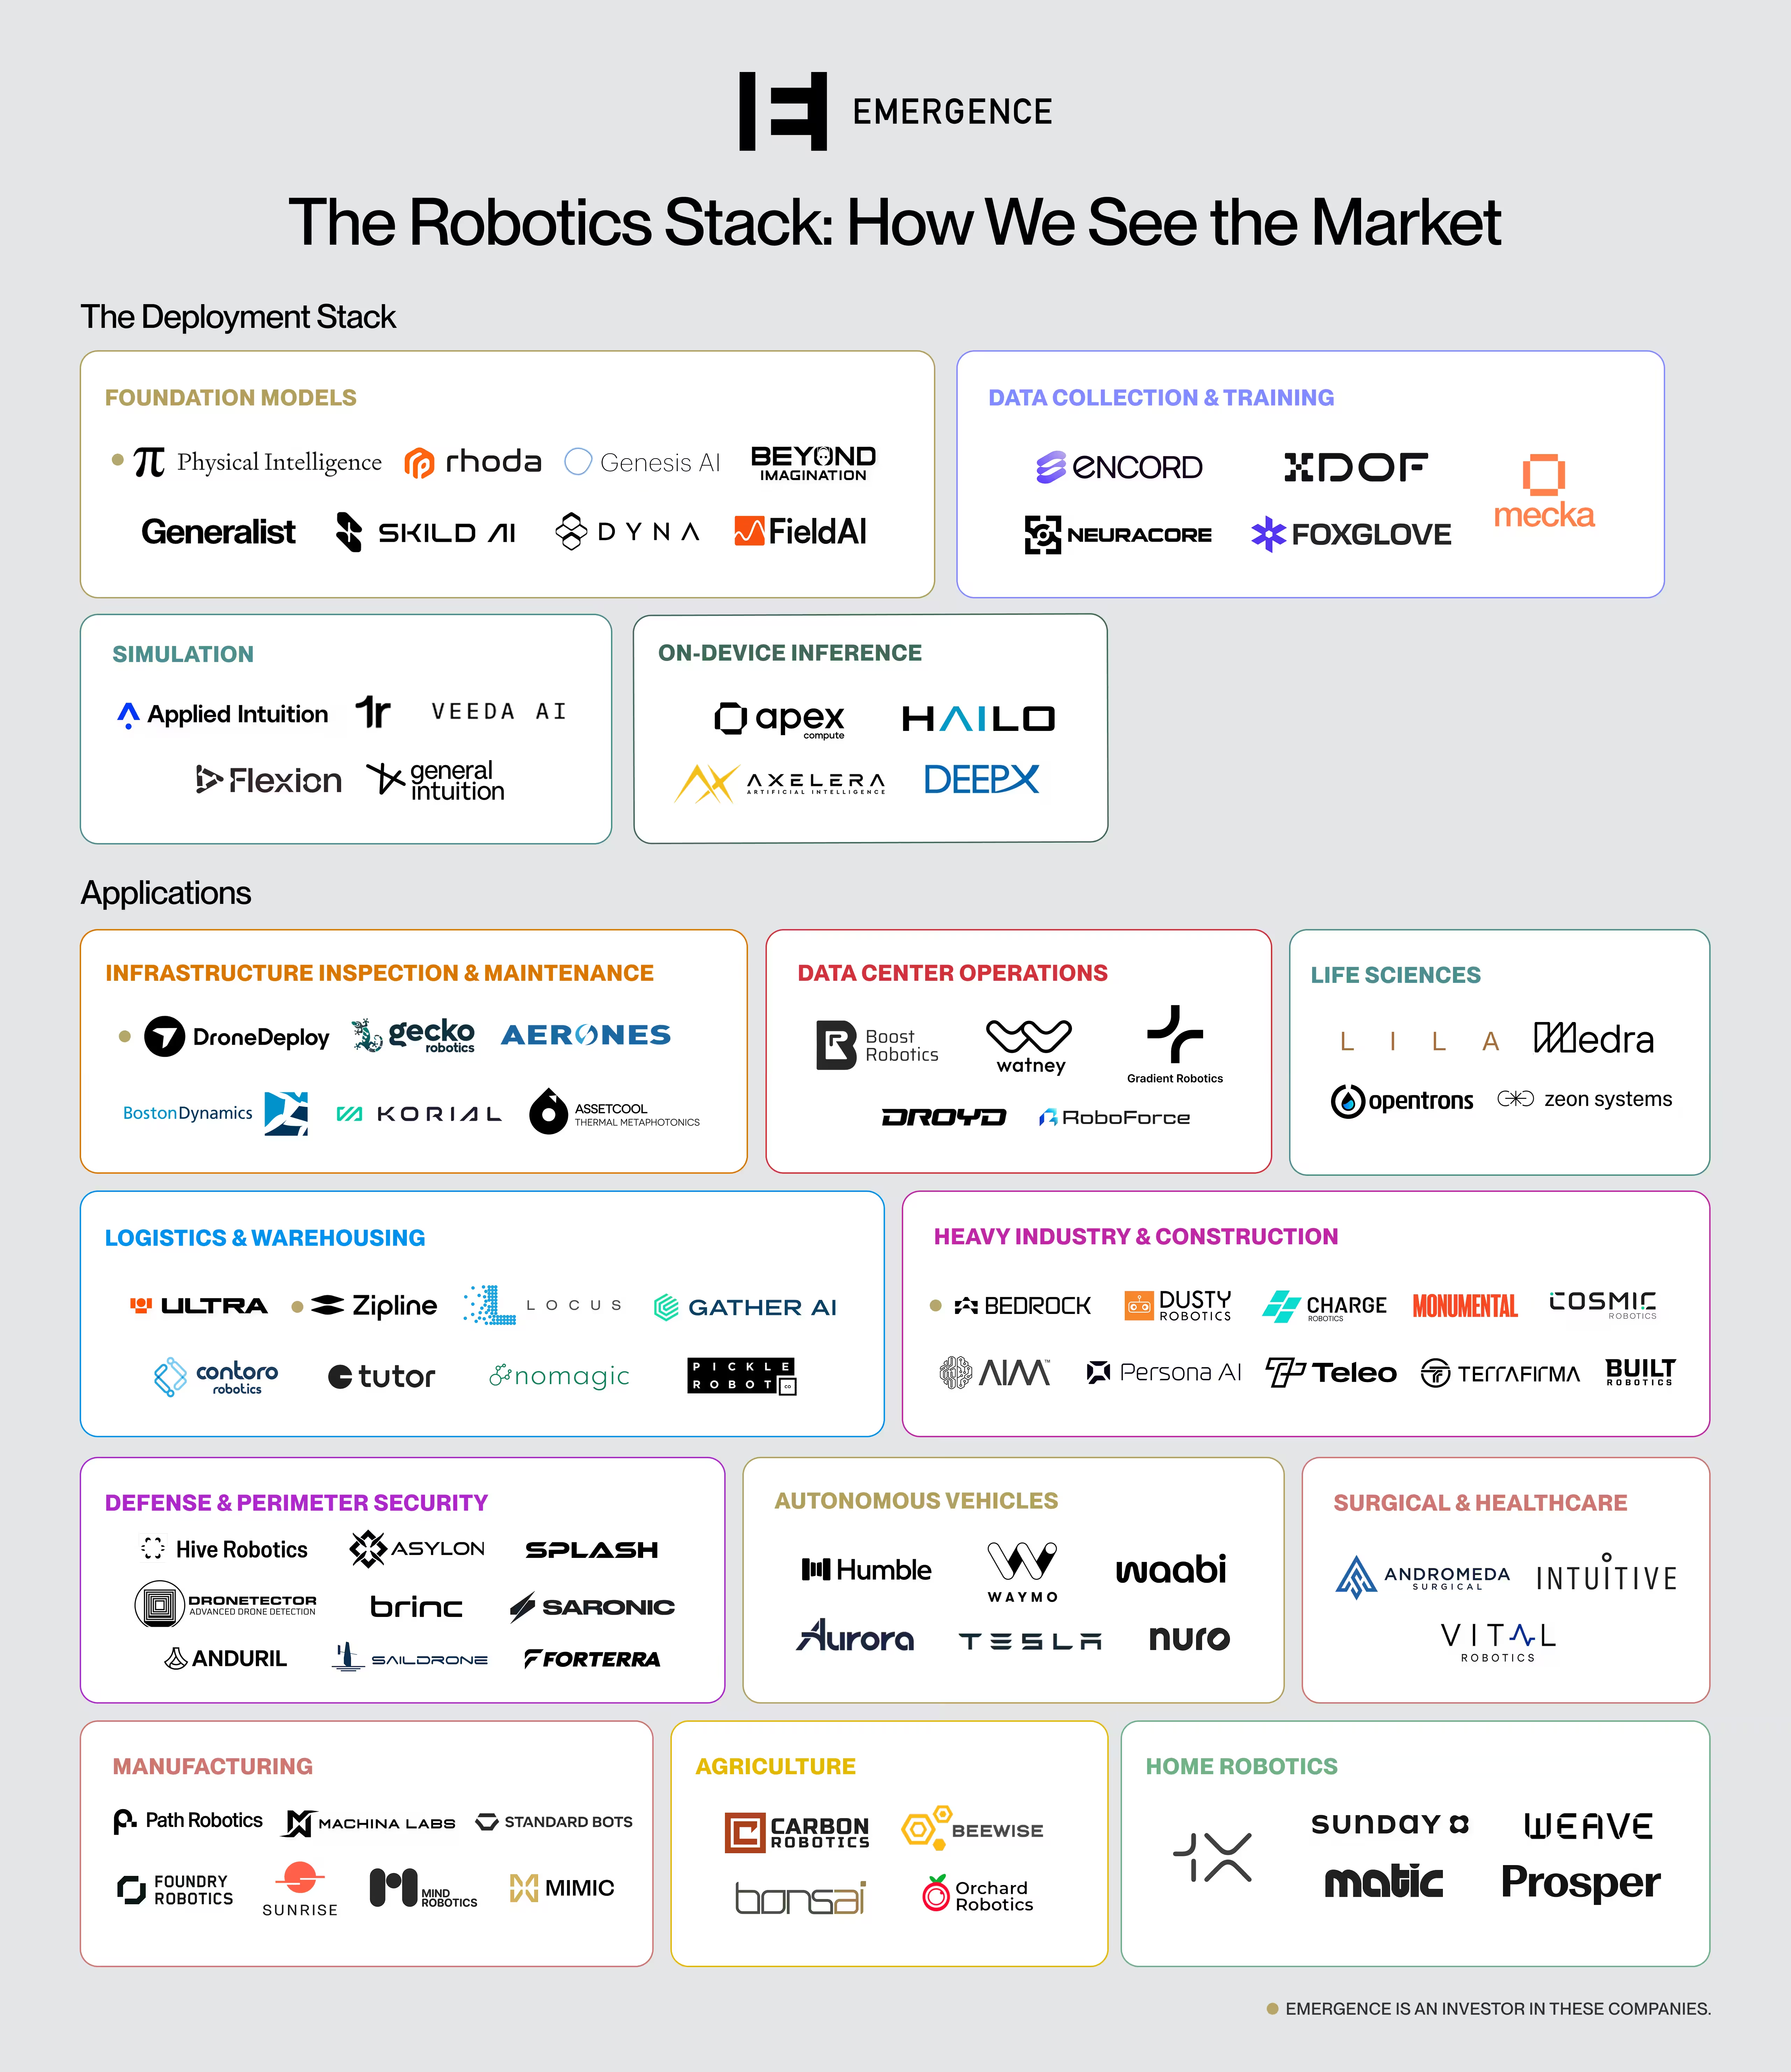
Infrastructure: The Deployment Stack
Foundation Models
The bet that a single model can generalize across robots, tasks, and environments rather than requiring task-specific programming for each new use case. The most credentialed research teams in the world are working here. Progress at this layer would enable a true general-purpose robot. Companies to watch: Physical Intelligence*, Generalist, Skild AI, Field AI, Dyna Robotics, Genesis AI, Rhoda AI
Data Collection & Observability
You can't train a robot without data, and the data doesn't exist at scale yet. At a recent dinner we hosted with robotics founders, the sharpest debate was over which collection approach will scale: teleoperation, egocentric human video, world models, or UMI. Raw robotics data also requires structured annotation to become useful, and the annotation infrastructure for robotics is meaningfully less mature than what exists for language and vision. This gap needs to close for foundation models to scale. Companies to watch: XDOF, Encord, Mecka, Foxglove, Neuracore
On-Device Inference
Running models on the robot itself reduces latency and cloud dependency, which is critical for real-world deployment at scale. Memory constraints and thermal management are real and unsolved, but the trajectory points toward robots that can operate more autonomously as this layer matures. Companies to watch: Hailo, Axelera AI, DeepX, Apex Compute
Simulation
Synthetic training environments let teams generate robotic experience before real-world deployment, reducing the cost and risk of data collection. As simulation fidelity improves, it becomes a meaningful lever for accelerating the training pipeline. Companies to watch: Applied Intuition, Flexion, One Robot, General Intuition
Applications: Where Deployment Pays Off
Infrastructure Inspection & Maintenance
Structural labor scarcity in hazardous environments like wind turbines, pipelines, and power grid infrastructure isn't going away. US grids need up to $2 trillion in modernization investment by 2030 just to maintain reliability, per estimates cited by PwC. Dedicated robots have the potential to close the labor gap. Companies to watch: Boston Dynamics, Gecko Robotics, Aerones, DroneDeploy*, Energy Robotics (Korial), AssetCool
Data Center Operations
Goldman Sachs estimates the AI build-out will require roughly $7.6 trillion in infrastructure investment between 2026 and 2031 across compute, data centers, and power. The physical construction and operations behind that number create a labor bottleneck that hiring can't solve. Rack installation, cable routing, and thermal inspection are repetitive and precision-critical, making them a strong fit for robotic automation at scale. Companies to watch: RoboForce, Watney Robotics, Boost Robotics, Gradient Robotics, Droyd Robotics
Logistics & Warehousing
Warehouse labor costs a median of $18.12/hour nationally, and robot pricing is closing that gap faster than most other categories, but not evenly across use cases. Unloading, kitting, and assembly remain among the largest manual labor pools in the economy. Companies to watch: Ultra, Zipline, Locus Robotics, Pickle Robot, Nomagic, Gather AI, Tutor Intelligence, Contoro Robotics
Heavy Industry & Construction
Construction needs hundreds of thousands of additional workers each year just to meet demand, while its operator workforce ages out. The winning approach so far is retrofitting autonomy onto existing infrastructure: strapping hardware and software onto the excavators, dozers, and haul trucks contractors already own. Companies to watch: Bedrock Robotics*, Dusty Robotics, Charge Robotics, Teleo, Monumental, Persona AI, TerraFirma, AIM Intelligent Machines, Built Robotics, Cosmic Robotics
Defense & Security
Recent conflicts have made autonomous drones central to modern defense, and budgets are following: European Allies and Canada spent over $574 billion on defense in 2025, up nearly 20% year over year. Counter-drone capability is now mandatory, and we’re seeing innovation across the stack from software to hardware. Companies to watch: Anduril, Saronic, Saildrone, Asylon Robotics, BRINC, Splash
Surgical & Healthcare
With the US facing a shortfall of nearly 20,000 surgeons by 2036, an aging population, and hospital margin pressure, there are strong incentives to embrace robotic automation. Intuitive Surgical proved the model: hospital systems pay recurring contracts, and ROI is measurable in operating room throughput and complication rates. The next generation is building on that playbook. Companies to watch: Andromeda Surgical
Manufacturing
There is a shortage in skilled trades as US factory production ramps with reshoring efforts. Welding, metal forming, precision assembly, and other processes are ready for autonomous robots to significantly accelerate production timelines. Companies to watch: Path Robotics, Machina Labs, Standard Bots, Mind Robotics, mimic, Sunrise Robotics
Autonomous Vehicles
The most mature proof that embodied autonomy works at scale: robotaxis now complete hundreds of thousands of paid rides per week. Adjacent segments like trucking, middle-mile, and off-road will follow as technology and regulation mature. Companies to watch: Waymo, Tesla, Nuro, Aurora, Waabi, Humble Robotics
Agriculture
Farm labor is chronically scarce, input costs keep climbing, and growers will pay for solutions with measurable per-acre ROI. The robotics opportunity is large and will likely involve new solutions and retrofits of existing machinery. Companies to watch: Carbon Robotics, Beewise, Bonsai Robotics, Orchard Robotics
Life Sciences
Scientific labor is the scarcest input in drug discovery, and most of it goes to bench work. Lab automation could create a closed loop and make wet-lab work more verifiable: hypothesize, robotically execute, analyze, repeat. Companies to watch: Lila Sciences, Opentrons, Medra, Zeon Systems
Home Robotics
The largest consumer TAM in robotics is likely the home robot, but safety and reliability concerns must be solved before the category goes mainstream. What's changed is price and form factor: home robots now ship at price points approaching high-end appliances, and general models are improving enough to cover basic home tasks. Companies to watch: 1X Technologies, Sunday, Matic, Weave Robotics, Prosper Robotics
What's Next: The Bottleneck Series
What has to be true for autonomous robots to actually proliferate throughout the economy? The honest answer is that multiple layers of the infrastructure stack remain underdeveloped at the same time, and that compound problem is what makes deployment so hard today.
Over the coming months, we'll publish a series on the bottlenecks we believe matter most: the software stack robots are built and run on, and why it's due for replacement; the gap between cheap hardware and hardware that survives real deployments; and the policy choices that will determine whether the US builds a robotics ecosystem or imports one. Our conviction is that these aren't permanent constraints. They're the solvable problems that will define the next wave of company creation in this space.